
EDGE turns data from accounts on your core and with other financial institutions into income and risk attributes that enable real-time verification, higher-precision risk assessment, and early warning signals — all so you can approve more applications with higher confidence, price more competitively to achieve higher conversions, and catch financial stress before members default.





Fewer stipulations
Less abandonment
More real-time approvals
Better access for members with thin or
no credit file
Default-neutral decisions across credit spectrum
Intervene sooner
before delinquency
More targeted retention
and relief offers
Reduced charge-offs
and collection costs
Automatically detect underwritable paystreams in any financial account
Bureau-like analytics based on banking activity and balance behaviors
Factors in member profile and account histories often considered in underwriting
Target direct mail and calling with analytics based on individualized cashflow insights
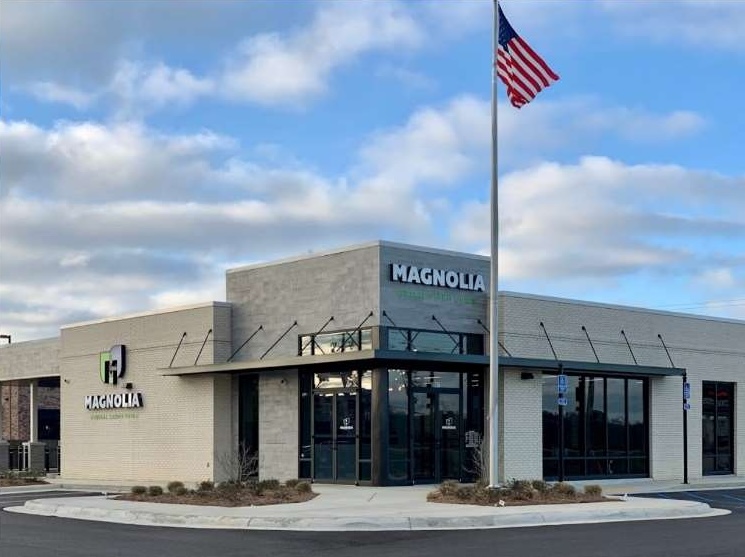
By embedding cashflow insights into underwriting, Magnolia FCU reduced manual review, surfaced risk earlier, and confidently approved more members with non-traditional income.
Buy Now, Pay Later plans (BNPL) have seen
explosive growth, with an estimated 1 in 5
Americans utilizing BNPL in 2024.

EDGE CEO Brian Reshefsky moderated a panel that included Amy Demkey, SVP of Lending at Trius FCU and the CEOs of Akoya and FairPlay on the opportunities and challenges of open banking for credit unions.
Deliver best-in-class care with a more complete picture of members’ financial health.
EDGE is a consumer reporting agency that delivers income verification and credit risk insights to credit unions and other financial services providers who primarily lend to unserved and underserved populations.
Real-time cashflow insights for smarter lending, better pricing, and stronger member relationships.

Today, we're diving into the world of storefront lending and how automation is transforming the game. We'll explore the incredible advantages of automation and how it's paving the way for more efficient, customer-friendly, and data-driven lending processes.

In the world of lending, making sound decisions is paramount. A borrower's income is a critical factor in assessing their creditworthiness and ability to repay a loan. Lenders require effective tools to evaluate this key aspect of every loan application. Enter EdgeIncome, a solution that empowers lenders to make informed decisions while streamlining their operations.

Bank transaction-based credit risk underwriting revolutionizes lending by providing valuable insights into borrowers' repayment abilities, and EdgeScore excels as a leading predictive risk score in accurately assessing risk across the credit spectrum.

Verification of income has traditionally been one of the most expensive and time-consuming steps in a loan application. With the innovation of instant bank verification (IBV), proof of income can be achieved in near real-time along with a host of risk insights relevant for credit decisions.

Edge, using its industry-leading data lake, has gained valuable insights into the influence of Buy Now Pay Later (BNPL) on various credit types. Proprietary research reveals that borrowers engage in familiar patterns such as loan stacking, increased borrowing during financial stress, and heightened default risk due to additional obligations.

Buy Now, Pay Later plans are frequently in the headlines for opportunities and risks alike. BNPL obligations pose a challenge for other lenders because they are largely unreported to credit bureaus. However, these liabilities can be reliably found in bank transaction data – an essential step in decisioning on a complete picture of consumer risk.

Traditional credit scores are inadequate for assessing risk in nearly half of the U.S., while analyzing cash flow behaviors in checking and savings accounts provides a more comprehensive financial picture, leading to actionable insights that enhance underwriting decisions.